Categories
Newsletter ArticlesPublished September 14, 2026
What Should I Know About Selling a Home With an Assumable Mortgage?
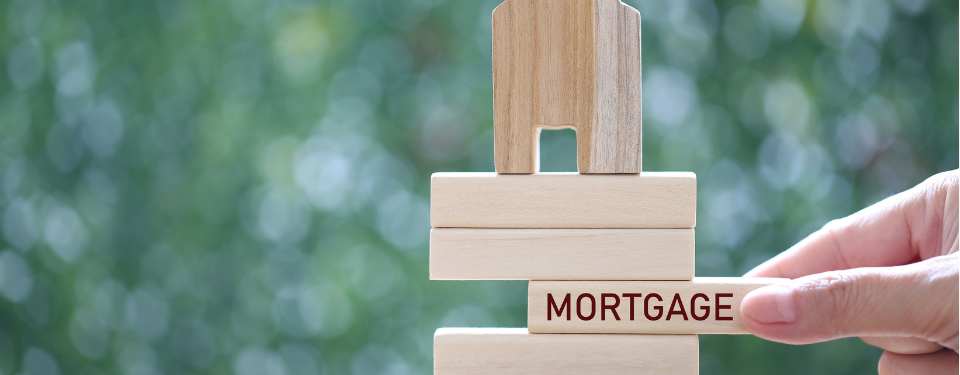
If your Huntington Beach home carries a mortgage with a particularly favorable interest rate, especially one significantly below current market rates, understanding whether your loan is assumable could represent a genuine, meaningful selling advantage.
Understanding What an Assumable Mortgage Actually Means
A buyer can take over your existing loan, including its interest rate and terms. Rather than obtaining entirely new financing, an assumable mortgage allows a qualified buyer to essentially step into your existing loan, inheriting its specific rate and remaining terms.
Not all loans are assumable. This feature is generally specific to certain loan types, most commonly FHA and VA loans, discussed in a related article in this series, while most conventional loans typically do not offer this option.
Why This Can Be a Genuine Selling Advantage
A significantly below-market interest rate becomes a real, quantifiable asset. If your rate is notably lower than current market rates, a buyer assuming your loan could save substantially on their monthly payment compared to obtaining new financing at current rates.
This can broaden your buyer pool in a higher-rate environment. When current market rates are elevated, buyers actively seek out homes with assumable loans offering this specific advantage, potentially generating stronger interest than a comparable home without this feature.
Understanding the Assumption Process
The buyer must generally qualify with your lender. Similar to obtaining new financing, a buyer assuming your loan typically needs to meet your lender's specific credit and income qualification standards.
The buyer needs to cover the difference between your loan balance and the purchase price. Since the buyer is taking over your existing loan balance rather than financing the full purchase price, they need to cover this gap, often through a larger down payment or secondary financing.
Your lender's specific assumption process and any fees apply. Understanding your specific loan servicer's requirements and any associated fees for processing an assumption is worth confirming directly if you believe this feature might apply to your loan.
How to Determine If Your Loan Is Assumable
Review your original loan documents or contact your loan servicer directly. Confirming this feature definitively, rather than assuming based on general loan type categories alone, ensures you have accurate information for your marketing strategy.
Marketing This Feature Effectively
If you do have a genuinely assumable loan with a favorable rate, highlighting this specifically in your marketing, with guidance from your agent on how to present this advantage clearly, can meaningfully differentiate your listing.
An assumable mortgage with a strong rate can be a genuine, valuable selling point worth confirming and marketing clearly.
If you believe your Huntington Beach home might have an assumable mortgage, Jeanette Nelson can help you confirm this and market this potential advantage effectively.
Jeanette Nelson
Keller Williams Realty
DRE: 01397168
713-366-8575
JeanetteNelson.com
Jeanette Nelson
| Jeanette Nelson Real Estate | Keller Williams Realty Huntington Beach
or another way